USDA Loans in Itasca County: Zero Down Explained
Published · By Malcolm Wallaker, Realtor, Pemberton Real Estate
Yes, USDA loans can get you into a home in parts of Itasca County with zero down, as of September 2026. The catch is the property has to sit inside a USDA-eligible rural area and be the home you actually live in, not a weekend lake cabin. I’m Malcolm Wallaker, I sell real estate here in the Grand Rapids area, and I walk buyers through this program every year.
What Exactly Is a USDA Loan
A USDA loan is a mortgage backed by the U.S. Department of Agriculture’s Rural Development program. It’s built to help moderate income buyers get into homes in rural areas without saving up a down payment. No down payment is required, but you still pay closing costs and a guarantee fee that gets rolled into the loan or paid monthly. Rates and fees change, so always confirm current numbers with your lender before you get your hopes up on a specific payment.
Does Grand Rapids or Your Town Actually Qualify
This is where people get tripped up. USDA eligibility isn’t about the whole county, it’s address by address, based on population and how rural an area is officially considered. Grand Rapids itself sits close to the population line where eligibility can change, so some addresses inside city limits may not qualify even though the surrounding township does. Smaller towns and outlying areas tend to have better odds, think Cohasset, Bigfork, and out toward Deer River. The only honest answer is to plug the exact address into the USDA eligibility map before you fall in love with a listing.
Income Limits: Can You Even Qualify
USDA loans cap how much household income you can have, and that limit is based on county and household size. These numbers get updated periodically, so I’m not going to guess at a dollar figure here, because a number I write today could be wrong by the time you read this. Check the current limits on the USDA Rural Development site or ask a loan officer to run your household numbers, it takes them about five minutes.
The Big Catch for Lake Home Buyers
Here’s the part that catches a lot of people who come to me wanting a place on the water. USDA loans require the home to be your primary home, the place you actually live most of the year. That rules out using this program to buy a second home or a seasonal cabin, no matter how rural the lake is. If you’re planning to actually live full time on a more remote lake, something out toward Trout Lake or one of the lakes further from town, it might be worth checking eligibility, but if the plan is weekends only, USDA is not going to work and you should look at the lakes comparison page to think through other financing paths.
How USDA Stacks Up Against Other Loan Options
Buyers usually ask me how USDA compares to FHA, conventional, or VA loans. Here’s the general shape of it, but confirm exact terms with your lender since guidelines shift.
| Loan Type | Down Payment | Mortgage Insurance | Property Location Rule | Best For |
|---|---|---|---|---|
| USDA | 0% | Guarantee fee, ask lender for current rate | Must be USDA-eligible rural area | Primary home buyers with moderate income |
| FHA | As low as 3.5% | Insurance premium, often for life of loan | None | Buyers with lower credit scores |
| Conventional | As low as 3-5%, varies by lender | Private mortgage insurance until enough equity built | None | Buyers with solid credit and some savings |
| VA | 0% | None monthly | None | Veterans and active military |
Steps to Take If You Think You Qualify
Start with the USDA eligibility map for the specific address, not just the town name. Then talk to a lender who actually closes USDA loans regularly, because not every loan officer works with the program often and the paperwork has some quirks. From there, get pre-approved before you start touring homes, because a USDA pre-approval letter carries real weight with sellers around here. I always tell buyers going this route to read the relocation guide first, since moving to a rural area comes with its own list of questions beyond just the loan.
Mistakes Buyers Make With USDA Loans in Itasca County
The biggest mistake is assuming a whole town is either in or out. Eligibility can change street by street, so a house on one road might qualify while a house two miles away doesn’t. The second mistake is falling for a lake property thinking it will work with USDA, then finding out at underwriting that it’s a second home or the area isn’t eligible. And the third is waiting too long to check income limits, only to find out midway through the process that a raise or a second job pushed the household over the line. None of these are deal killers if you catch them early, they’re only problems if you find out after you’ve written an offer.
If you want to figure out whether a specific address in Itasca County actually qualifies for zero down financing, call or text me at (218) 259-9837 and we’ll sort it out together.
Questions people ask
Does Grand Rapids, Minnesota qualify for a USDA loan?
Some addresses inside and around Grand Rapids do, and some don't, because USDA eligibility is set address by address, not by town name. As of September 2026, the safest move is checking the exact property on the USDA Rural Development eligibility map before assuming either way. I check this for buyers all the time and it genuinely varies block by block near the city line.
Can I use a USDA loan to buy a lake home in Itasca County?
Only if that lake home will be your actual primary home, since USDA loans don't allow second homes or vacation properties. If you plan to live there full time and the address falls in an eligible rural zone, it could work, but a weekend cabin will not qualify. Malcolm Wallaker recommends checking eligibility before writing an offer on anything you plan to use part time.
What credit score do I need for a USDA loan?
USDA loans generally allow for more flexible credit than conventional loans, but exact minimums are set by individual lenders, not a single fixed number. Most buyers I work with have decent, not perfect, credit when they go this route. Talk to a lender who closes USDA loans regularly to get a real answer for your situation.
How do I check if a specific property in Itasca County is USDA eligible?
Use the USDA Rural Development eligibility website and enter the exact street address, not just the city or zip code. Eligibility maps get updated periodically, so a property that didn't qualify a year or two ago might qualify now, or vice versa. Malcolm Wallaker checks this for clients as part of narrowing a search before touring homes.
Are there income limits for USDA loans in Minnesota?
Yes, USDA loans cap household income based on county and household size, and those limits are updated periodically. There's no fixed dollar figure worth repeating here since it changes, so verify the current number directly with USDA or a local lender. Household income above the limit is one of the most common reasons buyers get disqualified late in the process.
What is the difference between a USDA loan and an FHA loan?
USDA loans allow zero down payment but require the home to sit in an eligible rural area and be your primary home, while FHA loans allow around 3.5% down with no location restriction. FHA also tends to have mortgage insurance that lasts longer than the USDA guarantee fee structure. Which one makes sense depends on your income, credit, and where the home you want is located.
Can I use a USDA loan on a fixer-upper in Itasca County?
USDA offers a repair and rehabilitation loan option in some cases, but standard USDA purchase loans generally expect the home to be in decent, move-in condition. If a property needs major work, ask your lender specifically about USDA's rehab program versus other renovation loan options like an FHA 203k. Malcolm Wallaker can point you toward homes in Itasca County that are more likely to sail through a standard USDA appraisal.
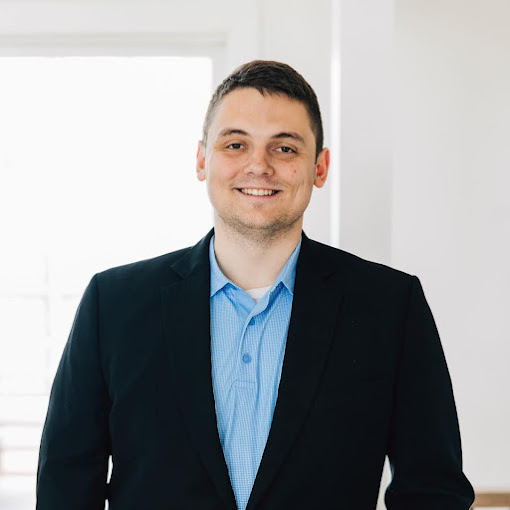
Malcolm Wallaker
Realtor, Pemberton Real Estate. 250+ career sales across Northern Minnesota. More about Malcolm →
Have a question this post didn't answer?
Call or text me and ask it. That's genuinely the fastest way to get a straight answer about anything up here.
Call (218) 259-9837